All Categories
Featured
Optimizing IUL Growth Potential for Retirement
Finding Cheap Individual Health Insurance Quotes
Optimizing IUL Growth Potential for Retirement
Table of Contents
An HMO Medicare Benefit plan supplies a network (described as an "HMO network") of health care providers and medical facilities to its clients. It's needed for a client to select a primary care physician to handle their healthcare and offer referrals to any providers that are not in the strategy's network, except in case of an emergency situation.
Not as numerous claims to file due to in-network care. The ease of having a medical care doctor to collaborate and handle the care provided. Typically, lower expenses for prescriptions. A client can only see companies within the plan's network unless they have a referral for an outside expert, or it's an emergency circumstance.
Nevertheless, unlike an HMO strategy, a PPO Medicare Benefit plan permits more flexibility when seeing out-of-network service providers. For that reason, it's not needed to have a referral to see an out-of-network specialist although it may be more expensive and take extra time to get insurance coverage because a patient must submit a claim for protection each time they see an out-of-network provider.
The patient has more versatility with which suppliers they choose to see, whether they're within the strategy's network or out-of-network. Many times, there is no requirement for a referral if a patient cares to see an out-of-network professional. Higher month-to-month premium. Probably, higher monthly premiums. The patient is accountable for managing their healthcare rather of a main care company.
An EPO insurance strategy, or an 'Exclusive Supplier Company' insurance coverage strategy, is often called a plan that is "located between an HMO and PPO." This is because, like a PPO strategy, an EPO does not need a patient to remain in-network for care significance, no recommendations or emergencies are essential for seeing an out-of-network company.
Evaluating PPO and HMO Medical Plans
This strategy is less widely understood, it often provides a much larger network than an HMO.A POS insurance strategy, or a 'Point of Service' insurance plan, is also known to "mix components of HMO and PPO plans." This is because, like an HMO plan, a POS insurance strategy requires a patient to have a medical care medical professional that handles their health care and provides them recommendations to out-of-network specialists or companies.
The Medicaid program offers Americans with low to no expense health care to individuals/households that have actually limited income or specials needs. Alongside Medicaid is a program called CHIP or 'Children's Health Insurance Program,' which is a state moneyed program where patients pay low to no expense healthcare for kids and pregnant women who have actually restricted earnings.
According to the IRS, the deductible is at least $1,400 for an individual and $2,800 for a household. In order to combat the high deductible expense, it is advised that a client contributes to an HSA/HRA or a 'Health Savings Account'/'Health Compensation Plan,' which companies typically contribute to annually.
Another element to note about this strategy is that it safeguards the client from "disastrous out-of-pocket expenditures for covered services." What this indicates is that, once a client's "yearly out-of-pocket expenses for covered services from in-network service providers, including deductibles, copayments, and coinsurance, reaches the established catastrophic limit," the insurance provider will cover all expenses.
HMO and PPO plans share specific functions. There are some primary distinctions in between HMO and PPO plans.
Strategic Financial Security Using Modern Life Insurance
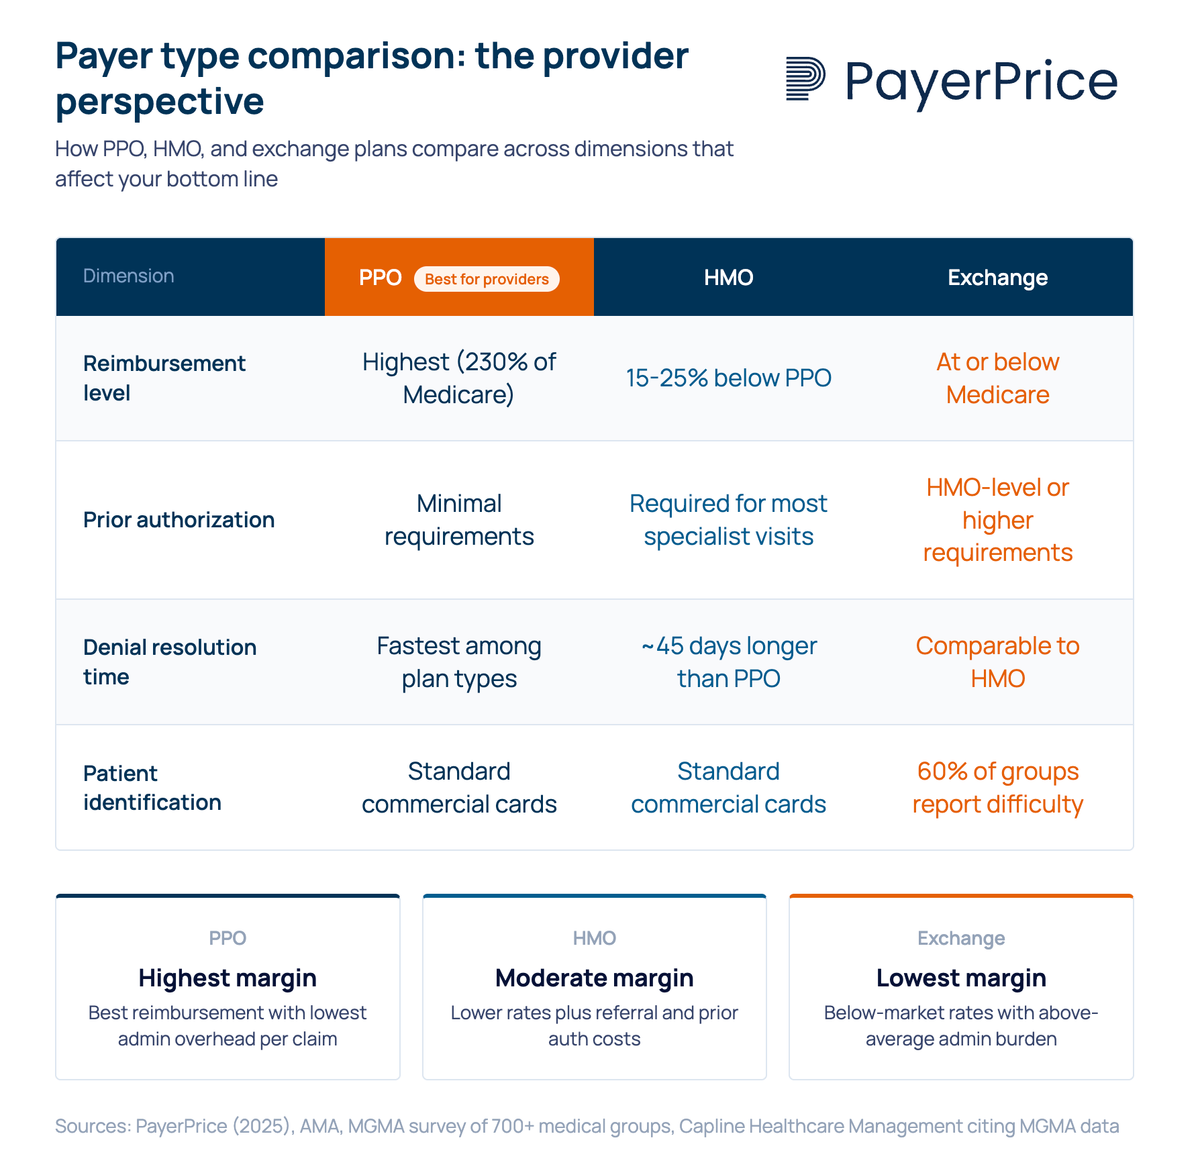
HMOs will not cover care from an out-of-network company. PPOs will, but you'll likely save when you remain in network. HMOs usually have lower premiums and out-of-pocket costs. PPOs may cost more, however they provide more flexibility.
Insurance in Buena Park CAWhen it comes to health insurance, you have your option of a number of strategy types. Distinctions between HMO (Health Upkeep Organization) and PPO (Preferred Company Organization) plans include network size, ability to see specialists, expenses, and out-of-network protection.

An HMO gives you access to specific medical professionals and medical facilities within its network. A network is comprised of suppliers that have actually agreed to decrease their rates for plan members and also satisfy quality standards. Unlike PPO plans, care under an HMO strategy is covered just if you see a service provider within that HMO's network.

Latest Posts

Comparing PPO Vs HMO Plans
Securing Burial Insurance Coverage
Optimizing IUL Growth Potential for Retirement